Seafreight
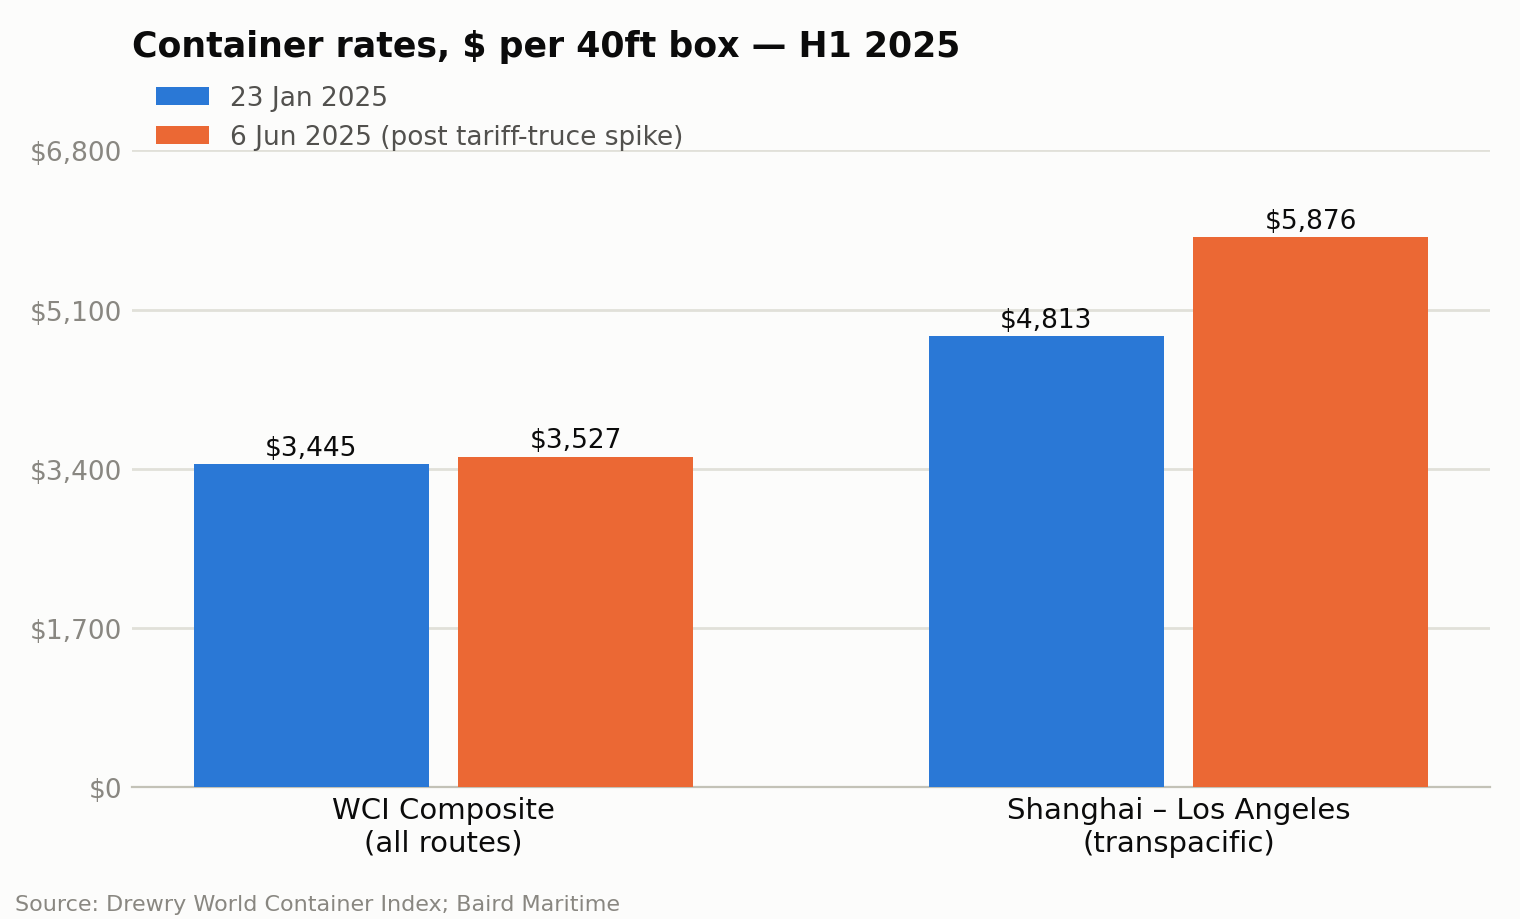
The first half of 2025 opened with a rare piece of good news: after the Gaza ceasefire, the Houthi in Yemen lifted their threat to international shipping (with the exception of Israeli-owned and -flagged vessels), and the Drewry World Container Index fell 11% in the week of 23 January to $3,445 per 40ft container. Shanghai–Rotterdam dropped to $3,434 and Asia–Mediterranean to $4,562. Even so, the big three carriers — Maersk, Hapag-Lloyd and MSC — said they would keep routing around the Cape of Good Hope "for the time being" rather than rush back to the Suez Canal, and rates drifted broadly sideways through February and March as Lunar New Year seasonality took hold.
The real disruption in H1 came from Washington, not the Red Sea. President Trump's "Liberation Day" tariffs, announced 2 April, pushed duties on Chinese goods as high as 145% and froze transpacific bookings almost overnight. The reprieve came just as fast: a US–China truce on 12 May cut tariffs back to 30% for a 90-day window, and shippers rushed to move cargo before the window closed.
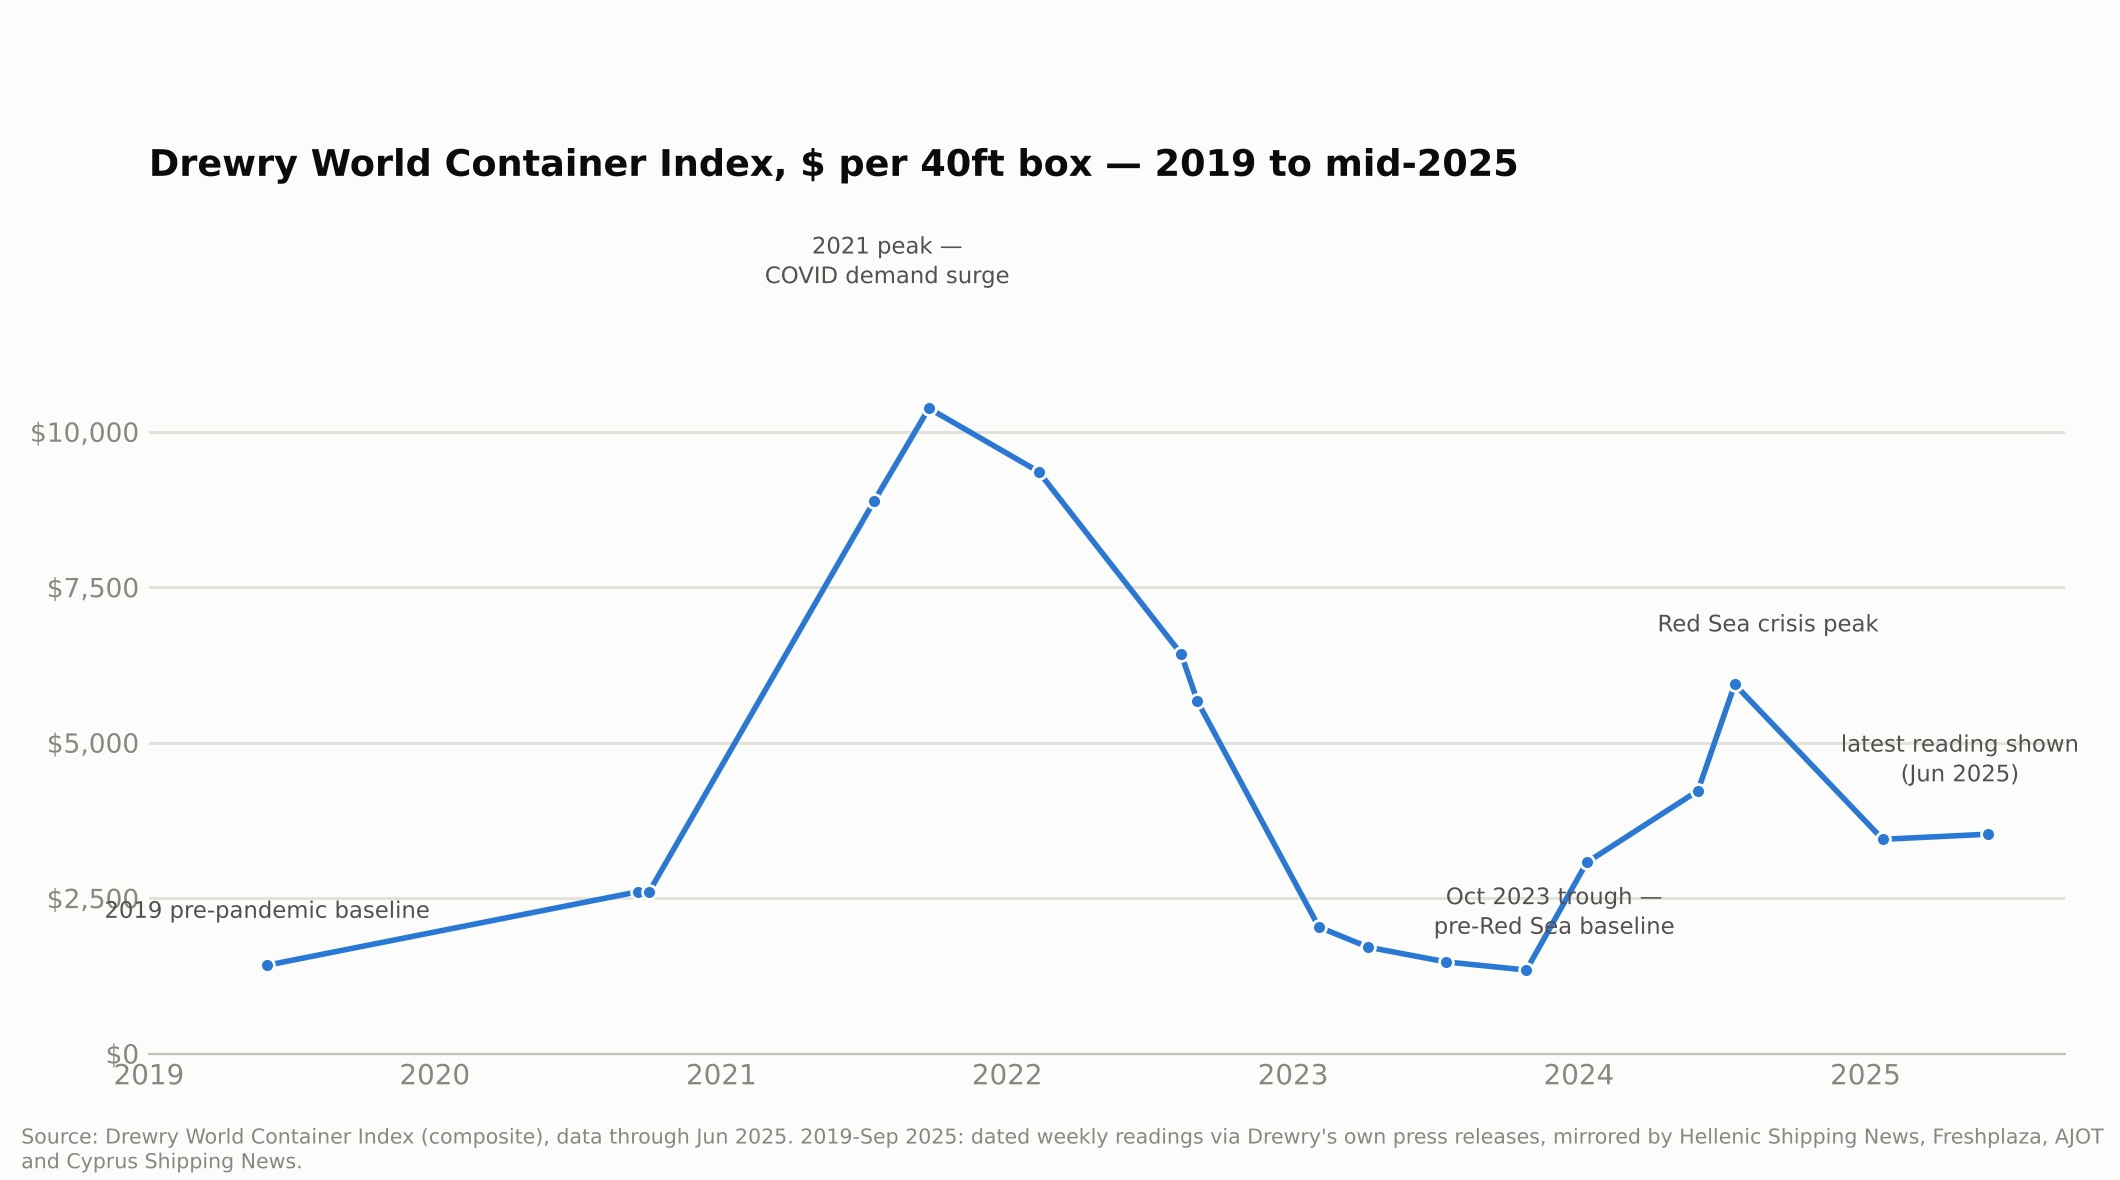
That rush produced the sharpest — if narrowest — spike of the half. By 6 June, the World Container Index had jumped 41% week-on-week and 70% over four weeks to $3,527, but the surge was concentrated almost entirely on US trades: Shanghai–Los Angeles rates more than doubled from early May, up 117% to $5,876 per FEU, while Asia–Europe pricing barely moved. Analysts flagged signs of the rally peaking even as it happened, with second-half-June quotes already softening.
On the Airfreight side of things:
Air cargo told a steadier story. Hong Kong–North America rates opened the year at $5.60/kg and Hong Kong–Europe at $4.68/kg, both easing through February as pre-Lunar New Year shipments were pulled forward into January rather than the holiday month itself. By March, Hong Kong–Europe had settled at $4.39/kg and Hong Kong–North America at $5.29/kg — both still comfortably up on 2024, though TAC Index noted that comparison was flattered by how strong 2024 already was on Red Sea disruption and e-commerce demand.
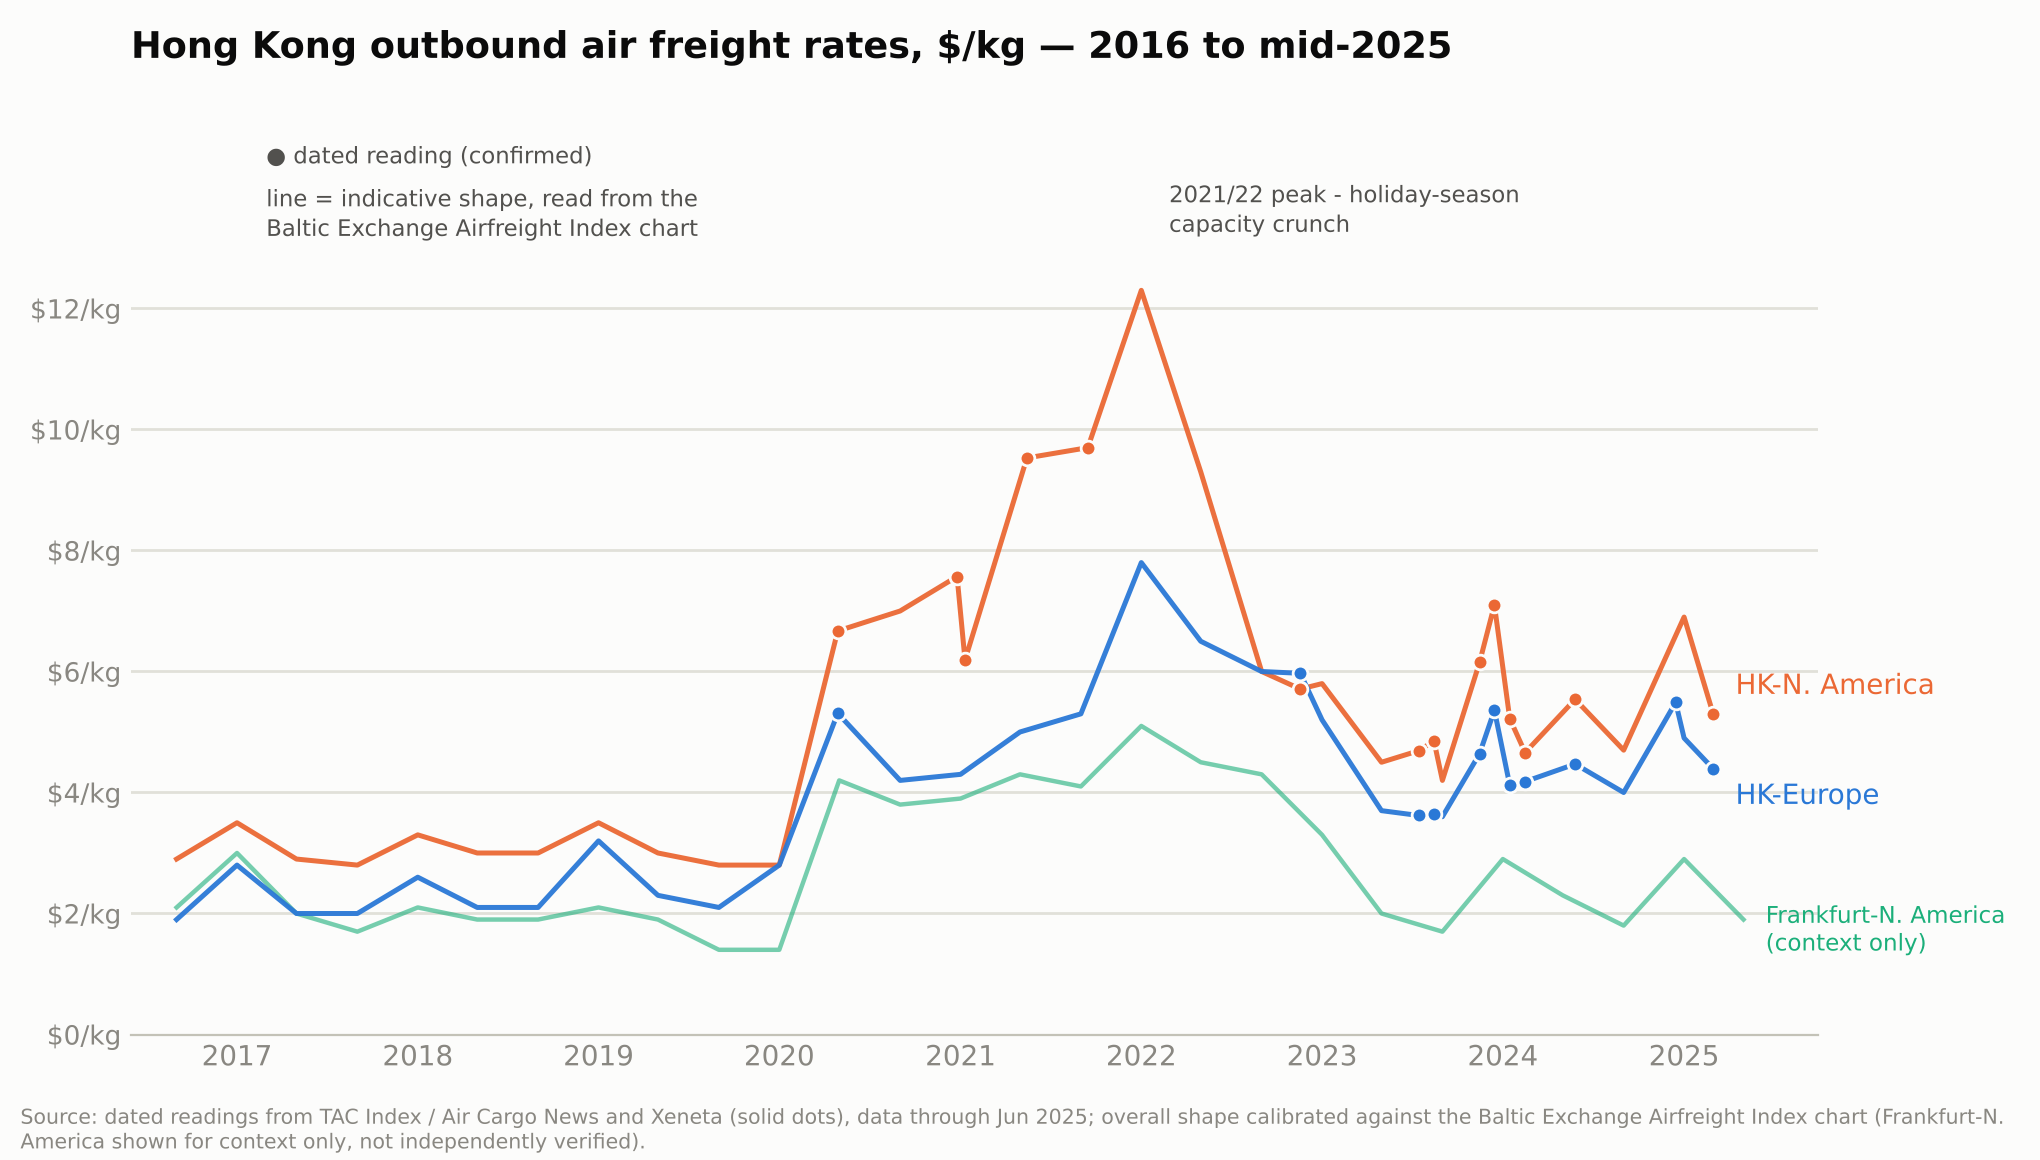
April's tariff shock hit transpacific air cargo just as it hit ocean freight, with North America rates sliding through the month before the May tariff truce sparked a partial rebound — spot rates rose more than $0.40/kg in a single week in mid-May as shippers again rushed cargo through the temporary 30% tariff window. That rush faded quickly: by June, Hong Kong–North America had eased to $4.99/kg (down 13.2% year-on-year, reflecting the new 30% tariff baseline and the end of the de minimis exemption) and Hong Kong–Europe to $4.36/kg, as extra bellyhold capacity arrived for the summer season and the market settled into what would prove a quiet third quarter.
Long-Term Perspective (2016–2026)
Zoomed out, the half described above is a minor ripple against a much larger cycle. Seafreight is still living in the shadow of 2021's COVID-era spike, when the Drewry World Container Index hit $10,377 per 40ft box — more than seven times the roughly $1,420 pre-pandemic baseline — before collapsing back below that baseline by October 2023. The Red Sea crisis then drove a second, smaller boom through 2024, and every swing since has played out within a narrower band than 2021's extremes, but still several multiples of the 2019 norm.
Air freight has followed the same rhythm, further back than the ocean data goes. Hong Kong–North America rates — flat around $3/kg for years before the pandemic — roughly doubled within weeks of COVID hitting in 2020, then kept climbing into a holiday-season blowout above $12/kg around the turn of 2022, the all-time high on record. They've spent the years since oscillating between $4 and $7/kg on a predictable seasonal rhythm (a January peak, a summer lull) that's repeated every year since — still routinely double the pre-pandemic baseline even in quiet periods, propped up first by e-commerce growth, then by the Red Sea's pull of cargo from sea to air, then by tariff-driven frontloading.